The War Machine Economy, Part 5: The Hidden Stake Already in Your 401(k)
You never bought a defense contractor or an AI chipmaker. If you hold an index fund, your retirement account already did it for you.
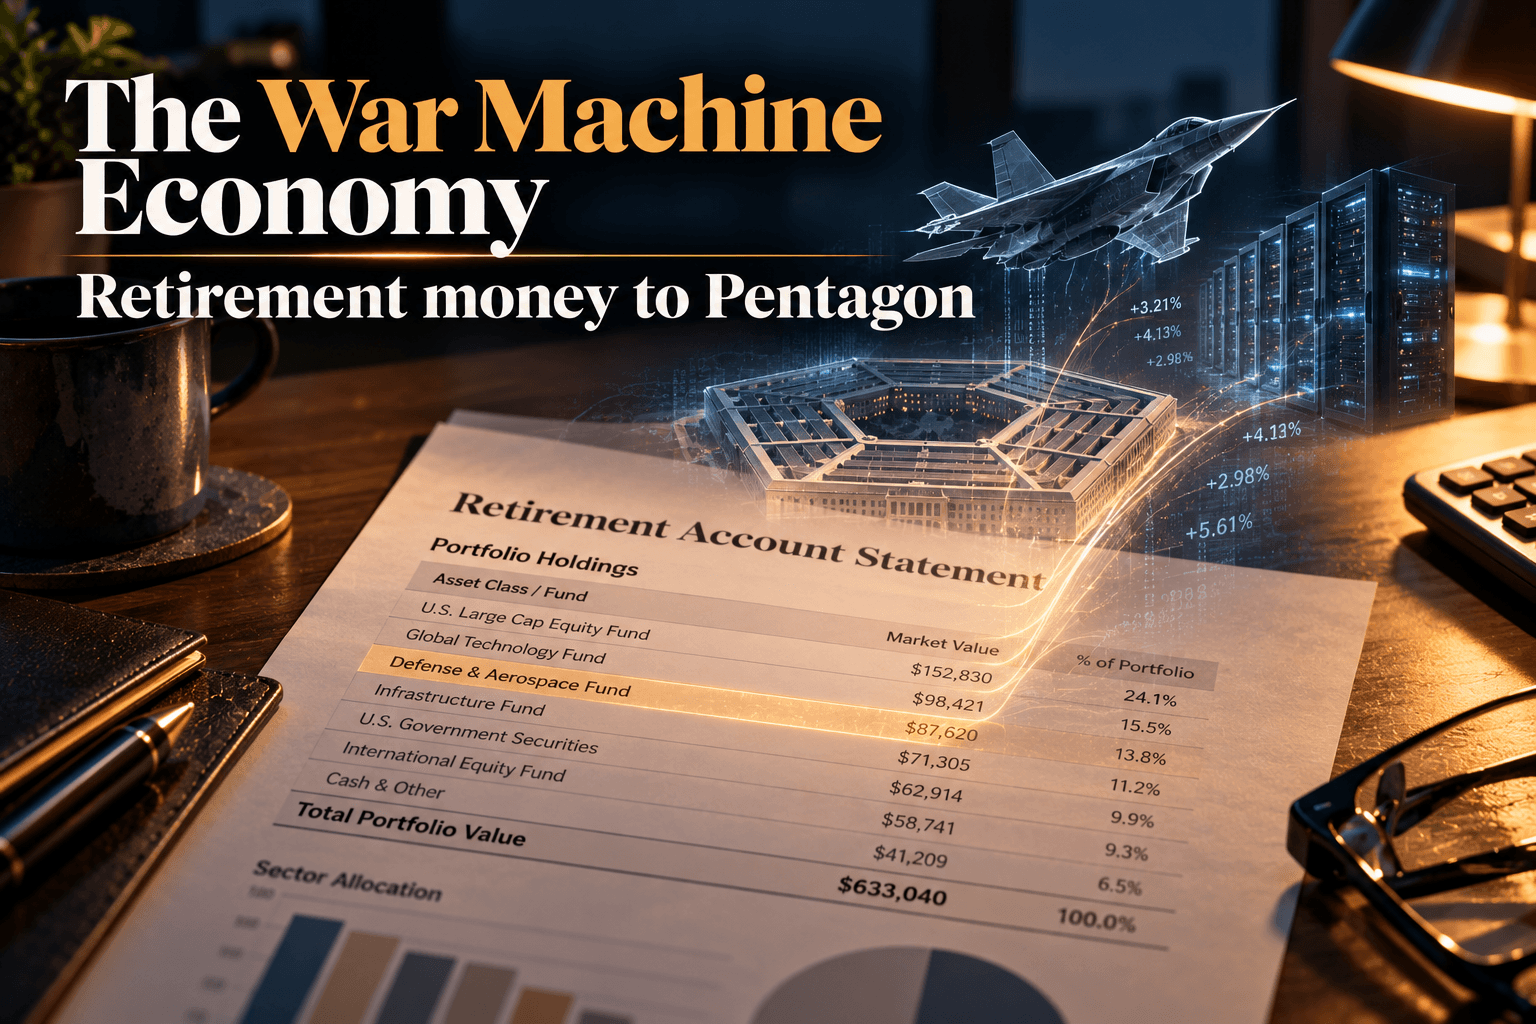
Somewhere in a plan document you probably never opened, a formula decided that a chunk of your retirement money would go to a company that builds AI targeting software for the Pentagon.
You didn't sign off on that. Nobody called to ask. If you hold a target-date fund, an S&P 500 index fund, or the default option in a workplace 401(k), the formula did it automatically, the same week your paycheck landed.
That formula is called index weighting, and it has spent the past two years quietly redirecting retirement money toward the companies building the defense-AI boom. You don't need to pick a defense stock to have a stake in it. Your index fund already picked one for you.
The Fund That Picks Stocks Without Picking Favorites
An index fund doesn't decide which companies deserve your money. It just mirrors the market, in proportion to size.
Think of it like a jar of mixed marbles, sorted not by color but by weight. The heaviest marbles take up the most room, automatically, without anyone sorting by hand.
The S&P 500 works the same way. It is "market-cap weighted," meaning each company's share of the index tracks its share of the index's total stock market value, which stood at roughly $61 trillion at the end of 2025. Grow bigger, and your slice of every index fund tracking the S&P 500 grows with you. No committee votes on it line by line.
That mechanic is why the index has become unusually top-heavy. Nvidia alone recently reached about 8 percent of the S&P 500's total weight, the largest share any single company has held since the index's modern form began in 1981.
The Names Already Riding Along in Your Statement
Nvidia's rise wasn't really about gaming. It was a two-decade side bet on chips that turned out to be perfect for training AI, a story this series explored in how a graphics card company became the backbone of AI. That bet is now the single biggest lever on your index fund's daily return.
Palantir is newer to the index, and louder about its defense ties. S&P added it to the S&P 500 in September 2024, after years of building data and targeting software for the Pentagon and allied militaries. Shares jumped on the announcement alone, then kept climbing, finishing 2024 up 340 percent, the best return of any stock in the index that year.
Did You Know?
The Thrift Savings Plan, the retirement account for roughly 7 million federal employees and military service members, has its own version of this. Its flagship "C Fund" simply tracks the S&P 500. That means service members saving for retirement are, by default, part owners of the same defense and AI contractors some of them may serve alongside.
Lockheed Martin and RTX, the two biggest pure-play defense primes in the index, sit at the other end of the scale. Index-tracking data puts Lockheed Martin at around 0.17 percent of the S&P 500's total weight and RTX somewhat higher, each a small fraction next to Nvidia's. They're real holdings in a broad index fund, just small ones.
Anduril, the newer defense-tech firm building drones and autonomous weapons systems, isn't in any of these funds at all, because it's still privately held. Its funding round in June 2025 valued it at $30.5 billion. A Series H round in May 2026, led by Thrive Capital and Andreessen Horowitz, reportedly doubled that to $61 billion, according to multiple outlets covering the deal, though a private valuation like this isn't audited the way a public company's market cap is. Until Anduril goes public, index investors own Nvidia's and Palantir's slice of the AI-defense story, not Anduril's.
How Much of Your Return Already Came From This Bet
This isn't a rounding error. Through late August 2025, Nvidia alone contributed about 2.4 percentage points of a popular S&P 500 fund's roughly 11 percent gain for the year, which works out to around a fifth of the fund's entire return coming from one company.
Picture a class project graded as a group, where one student does a fifth of the work. The whole group's grade still depends heavily on that one contribution, whether or not the rest of the group ever notices.
That's the shape of a modern "diversified" index fund now. It holds hundreds of companies, but a handful of AI-linked names, Nvidia chief among them, are doing an outsized share of the lifting, for better or worse.
A Boom Built Partly on Borrowed Money
The same AI buildout lifting these stocks is also being financed with a historic amount of corporate debt, as bond investors have started pricing into hyperscaler borrowing. That matters to an index investor too: a fund that owns the equity doesn't own the debt, but the two are tied to the same bet succeeding.
The Pentagon has leaned into that bet directly. In May 2025, it signed agreements with Nvidia, Microsoft, and Amazon to expand classified military use of their AI tools, on top of earlier deals with Google and SpaceX. Each contract is one more thread connecting ordinary retirement savings to the defense-AI economy, whether or not the saver ever reads a headline about it.
Vanguard's recordkeeping data shows roughly 61 percent of 401(k) participants now hold their retirement savings entirely in a target-date fund, up from under half a decade ago, largely because target-date funds are the automatic default when a worker is auto-enrolled. Most people never actively chose that fund. It was chosen for them, the same way the fund's underlying stocks are.
Why Nobody Notices Until the Statement Changes
It's not that people don't care where their money goes. It's that index investing was designed, correctly, to need no attention at all: pick a broad fund, keep contributing, and don't fiddle with it. That design is part of why money decisions tend to run on habit and emotion rather than close inspection, and a quarterly 401(k) statement is about as far from close inspection as personal finance gets.
That's not a flaw in the advice. "Buy a low-cost index fund and leave it alone" remains some of the soundest guidance in personal finance, precisely because it removes the temptation to chase headlines. But removing attention from the decision doesn't remove the decision. It just moves who's making it, from the saver to the index's weighting formula, and lately that formula has been tilting harder toward a small number of AI and defense names than it has in decades.
According to Investment Company Institute data, U.S. retirement accounts held a combined $49.1 trillion by the end of 2025, with 401(k) plans alone holding $10.1 trillion. A meaningful share of that money is now riding on whether the AI-defense boom keeps paying off, not because savers bet on it, but because the market did, and the index just followed.
Knowlegic Perspective
It's tempting to read a story like this as a warning to sell, or a tip to buy more. It's neither. Index funds are not a referendum on any one company; they're a mirror of the market as a whole, reflecting whatever investors collectively decide is valuable this year.
What's genuinely new is how much of that mirror is now filled by one trend. A fund built to spread risk across 500 companies currently has close to a tenth of its weight riding on a single chipmaker, with a Pentagon-backed data firm among its best performers two years running. That's not a hidden scandal. It's public information that almost nobody checks, because checking isn't what index investing asks of you.
The defense-AI economy this series has traced, the chip chokepoints, the Pentagon contracts, the hyperscaler debt, isn't confined to specialist portfolios or defense-sector ETFs. It already runs through the ordinary 401(k), the default target-date fund, the account most people fund and forget. You don't need to pick a defense stock to have a stake in the war machine economy. Your index fund already picked one for you.
Sources & References
- Nvidia Stock at 8% of the S&P 500 Index Is a Big Problem for Investors - Yahoo Finance (2025)
- Nvidia's Outsized Impact on the S&P 500 ETF (VOO) in 2025 - etf.com (2025)
- Nvidia is dominating the S&P 500 more than any company in at least 44 years - Sherwood News (2025)
- The top S&P 500 stock of 2024 returned 340.5%, and it wasn't Nvidia - CNBC (2025)
- S&P 500 Companies By Weight - US500.com, index-tracking data (2026)
- When 500 companies don't equal diversification: A TSP reality check - Government Executive (2025)
- Pentagon Teams With Nvidia, Microsoft, and AWS To Secure Classified Networks - Yahoo Finance / Fast Company reporting (2025)
- Anduril's Series G round and more venture moves to highlight - Washington Technology, citing Bloomberg (2025)
Enjoyed this?
Get notified when a new Knowlegic story worth knowing is published.


